
Five for Friday - December 6, 2024
12/6/2024
Consumer, Inflation, Debt Ceiling, Sentiment, and All-Time Highs
1. Consumer
The U.S. economy is roughly 70% consumption, so the investing world’s hyper-focus on the state of the U.S. consumer is generally warranted. A smattering of recent anecdotal data would suggest things are going just fine – from a historic box office weekend to record TSA throughput to the pop in consumer confidence to solid Black Friday and Cyber Monday spending numbers to the average national gas price falling to multi-year lows. If you want to move past anecdotal data to the stock market’s view of things, the Consumer Discretionary sector – which is filled with restaurant, leisure, and retail companies – hit a new all-time high this week (as did its equal-weighted variety, where Amazon is no more important than CarMax). By all accounts, the U.S. consumer continues to hum along. And importantly, the market seems to agree.
2. Forecasts
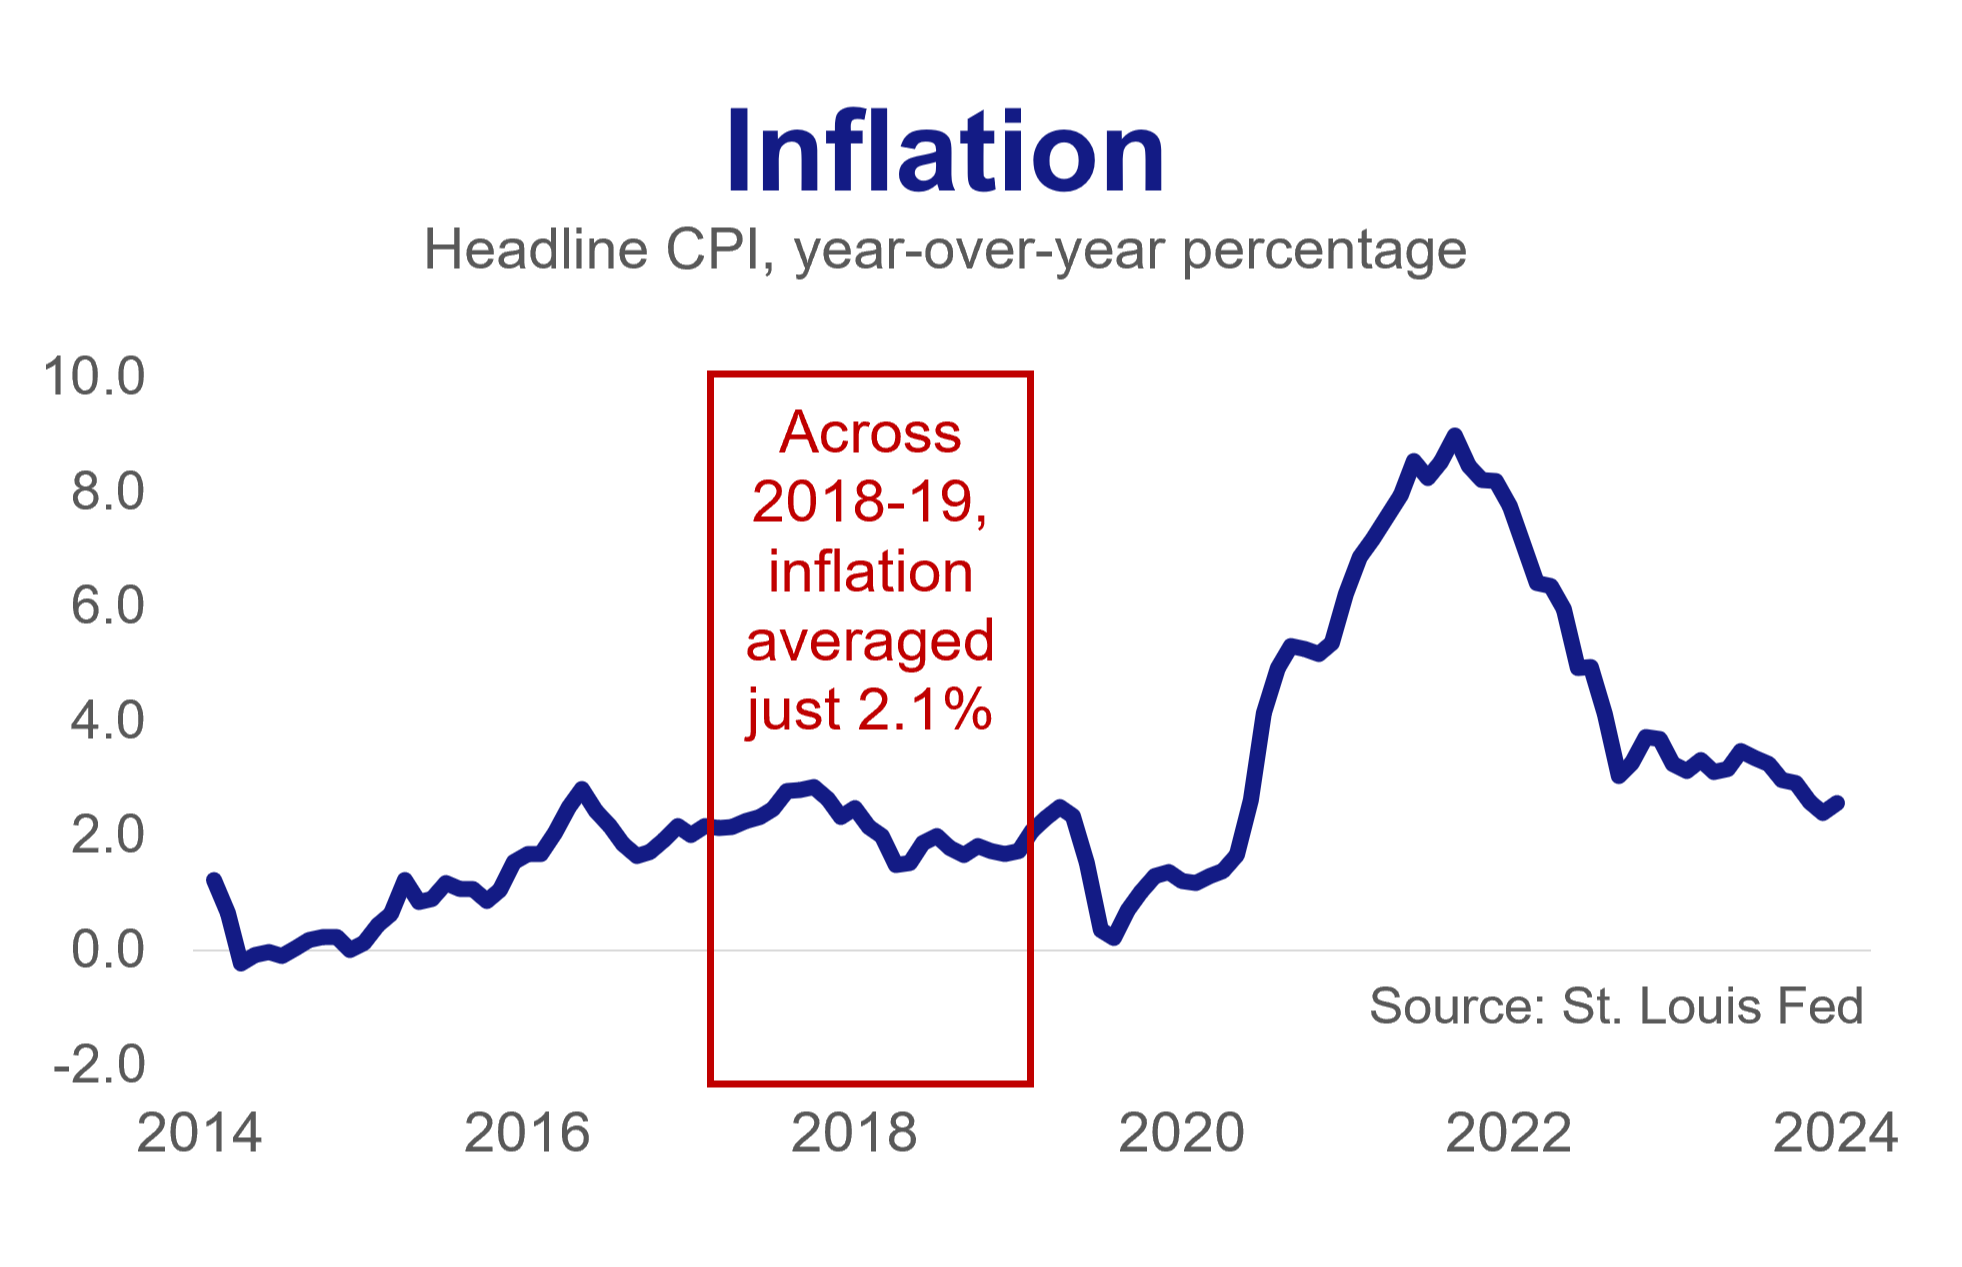
In next week’s All That Matters video, I make the (out of consensus) prediction that inflation will be lower than expected in 2025. While there is valid concern that President-elect Trump's tariff and tax policy will be inflationary, I think the fears are somewhat overblown. For one, during Trump's first term, even in the teeth of the trade war, inflation remained anchored around 2%. And second, while we should expect additional tariffs to be levied, the magnitude and breadth are yet undetermined (tariff threats were clearly a negotiating tool in Trump's first term, and his key appointments thus far have not been overly pro-tariff). Looking past trade, I think there are other reasons to expect the disinflationary trend to continue. For one, a “drill, baby, drill” approach to domestic oil and gas production could lead to lower prices at the pump (as could a push for peace talks in Gaza and Ukraine). Housing could also be a tailwind as the official data “catches down” to more timely measures (the official BLS reading often lags market rents significantly – while the BLS says rental costs are up 5% y/y, ApartmentList says asking rents are actually down). Ultimately, big macro predictions are difficult-to-impossible to get right with regularity, but if we are having a little fun looking ahead, I wouldn’t be too shocked if this one bore out.
3. Debt ceiling
The U.S. will hit the debt ceiling in a few weeks, which will halt new debt until Congress raises the limit—a course that has not always run smooth. You’d think that a fight over how much debt we have would lead to anxiety, but as Tom Tzitzouris at Strategas noted this week, bond markets will benefit from the government being forced to pay its bills from the Treasury General Account. We will go from a surplus of Treasury supply to a shortage (which could lower interest rates) and the influx of TGA cash will inject liquidity into banks and bank reserves. The more time that elapses before the debt ceiling is raised, the more it benefits the bond market as demand comes in and pushes yields down.
4. Rising
There’s been some anxiety over the percent of consumers who expect stocks to be higher in one year reaching a record level of 56% (the fear being, “people are too euphoric – this is a bubble bound to pop”). I’d push back on the idea that this is a reason for handwringing. Historically, U.S. stocks have been up over a 12-month period 76% of the time. So, if anything, even more people should regularly expect the market to be higher a year out, just based on math. The fact that 56% represents a multi-decade high likely means that negativity kept many on the sidelines of the recent bull market rallies. Frothy sentiment bears watching, but in my view it’s better to be invested than not.
5. Did you know?
After notching just one all-time high in 2022 and 2023, the S&P 500 has made 57 new all-time highs in 2024 (so far). Since 1928, only four years have had more: 1964, 1995, 2017, and 2021. A strong December (the 2nd best month for stocks, historically) could see 2024 continue to climb the list. Ultimately, this is just another way to categorize the current bull market, which is now up 76% since the market bottomed on Oct. 12, 2022 – but it’s a fun fact nonetheless.
Disclosures
The information offered is provided to you for informational purposes only. Robert W. Baird & Co. Incorporated is not a legal or tax services provider and you are strongly encouraged to seek the advice of the appropriate professional advisors before taking any action. The information reflected on this page are Baird expert opinions today and are subject to change. The information provided here has not taken into consideration the investment goals or needs of any specific investor and investors should not make any investment decisions based solely on this information. Past performance is not a guarantee of future results. All investments have some level of risk, and investors have different time horizons, goals and risk tolerances, so speak to your Baird Financial Advisor before taking action.
This is not a complete analysis of every material fact regarding any company, industry or security. The opinions expressed here reflect our judgment at this date and are subject to change. Market and economic statistics, unless otherwise cited, are based on data from FactSet. The information has been obtained from sources we consider to be reliable, but we cannot guarantee the accuracy.
This report does not provide recipients with information or advice that is sufficient on which to base an investment decision. This report does not take into account the specific investment objectives, financial situation, or need of any particular client and may not be suitable for all types of investors. Recipients should not consider the contents of this report as a single factor in making an investment decision. Additional fundamental and other analyses would be required to make an investment decision about any individual security identified in this report.
For investment advice specific to your situation, or for additional information, please contact your Baird Financial Advisor and/or your tax or legal advisor.
Past performance is not indicative of future results and diversification does not ensure a profit or protect against loss. All investments carry some level of risk, including loss of principal. An investment cannot be made directly in an index.
Baird does not currently recommend the purchase of any cryptocurrencies, products that attempt to track cryptocurrencies, or cryptocurrency custodians. Baird does not custody Bitcoin or any other cryptocurrencies.
Copyright 2024 Robert W. Baird & Co. Incorporated.
Other Disclosures
UK disclosure requirements for the purpose of distributing this research into the UK and other countries for which Robert W. Baird Limited holds an ISD passport.
This report is for distribution into the United Kingdom only to persons who fall within Article 19 or Article 49(2) of the Financial Services and Markets Act 2000 (financial promotion) order 2001 being persons who are investment professionals and may not be distributed to private clients. Issued in the United Kingdom by Robert W. Baird Limited, which has an office at Finsbury Circus House, 15 Finsbury Circus, London EC2M 7EB, and is a company authorized and regulated by the Financial Conduct Authority. For the purposes of the Financial Conduct Authority requirements, this investment research report is classified as objective.
Robert W. Baird Limited ("RWBL") is exempt from the requirement to hold an Australian financial services license. RWBL is regulated by the Financial Conduct Authority ("FCA") under UK laws and those laws may differ from Australian laws. This document has been prepared in accordance with FCA requirements and not Australian laws.


